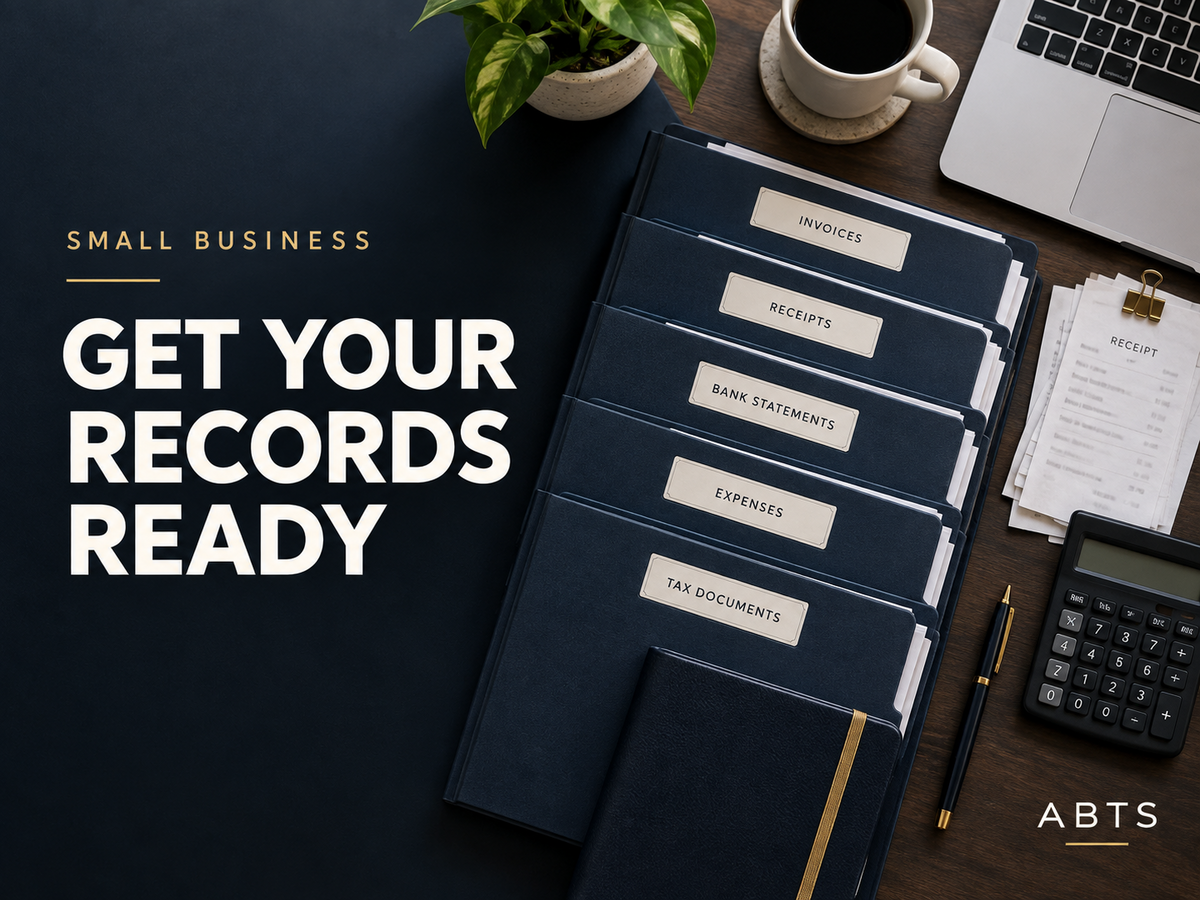
Tax time feels much heavier when business information is scattered. One receipt is in an email. Another is in a glove compartment. A customer payment appears in a banking app, but the matching invoice is somewhere else. None of this means you have failed. It means your recordkeeping routine needs one clear home and a few repeatable steps.
The Internal Revenue Service explains that good records can help a business monitor its progress, prepare financial statements and tax returns, identify sources of income, track expenses, and support items reported on a return. The IRS also says businesses may generally choose a recordkeeping system suited to them as long as it clearly shows income and expenses. In other words, the useful system is the one you can maintain and explain.
Here is a practical five-part starting point.
1. Choose one home for the year
Decide where business records will live. That might be a secure digital folder, bookkeeping software with attached documents, a physical filing system, or a combination that fits your business.
Create a clear structure for the year. Categories might include income, operating expenses, bank and credit-card statements, assets and equipment, payroll or contractor materials when applicable, and questions for your professional. The exact categories should reflect your business rather than someone else’s template.
2. Gather the main streams
Start by identifying where business information enters your day. Common sources include sales invoices, receipts, bills, deposit records, bank statements, credit-card statements, payment processors, and accounting software.
The IRS notes that purchases, sales, payroll, and other business transactions generate supporting documents used in the books. Your first goal is to bring those streams into the system—not to decide every tax question by yourself.
3. Match and label what you can
Connect supporting documents to the transactions they explain. A receipt should relate to the recorded payment. An invoice should be connected to the corresponding customer transaction or payment, as applicable. If the business purpose would not be obvious months later, add a short factual note while you still remember it.
Matching a payment alone does not decide its tax treatment. Keep the underlying support and save classification questions for a qualified professional.
4. Use a short review rhythm
A small weekly or monthly review is usually easier than rebuilding an entire year under pressure. Pick a recurring time to:
- file new documents;
- match obvious transactions;
- review bank and credit-card activity;
- identify missing support;
- note questions; and
- back up records appropriately.
IRS Publication 583 describes orderly, safe storage and gives organization by year and type of income or expense as an example. The point is consistency: you should be able to find the support for an entry without searching every device and drawer.
5. Prepare questions instead of guesses
Keep a running list of anything uncertain. Examples might include how to categorize an unusual purchase, what support is needed for a particular transaction, how to handle an asset, or how long a record should be retained.
There is no single retention period that fits every document and situation. IRS guidance says the length of time depends on the action, expense, or event recorded and how long the document is needed to support return information. Alabama businesses should also review current Alabama Department of Revenue resources for state-specific responsibilities.
A calmer next step
You do not need to solve everything in one sitting. Choose one record source today—perhaps one month of bank activity or one folder of receipts—and bring it into the system. Then set the next short review.
Organized records do not guarantee a particular tax result. They can, however, make your business information easier to understand, support, and discuss with a qualified tax or bookkeeping professional.
Follow ABTS Global for clear, practical financial education.
Educational disclaimer: This material provides general educational information and is not individualized tax, accounting, legal, or financial advice. Requirements and retention periods depend on the facts, record type, jurisdiction, and applicable period. Consult an appropriately qualified professional about your situation.